A rule tracked, not a transfer made for you.
Save without thinking about it. A rule triggered on every payday, a safety cushion, dated goals — and the gap to each one, always visible.
Yoseri is not open yet outside Canada.
This page describes the product as it works in Canada. The pension plans, the tax shelters and the connected banks here are Canadian: they do not transpose. Where you are, it would rather be the local public plan, with the local tax shelters as tax shelters and your tax administration opposite.
We do not claim to know those rules today — connecting them is work, not a translation. Tell us where you are: the order in which markets open is decided there.
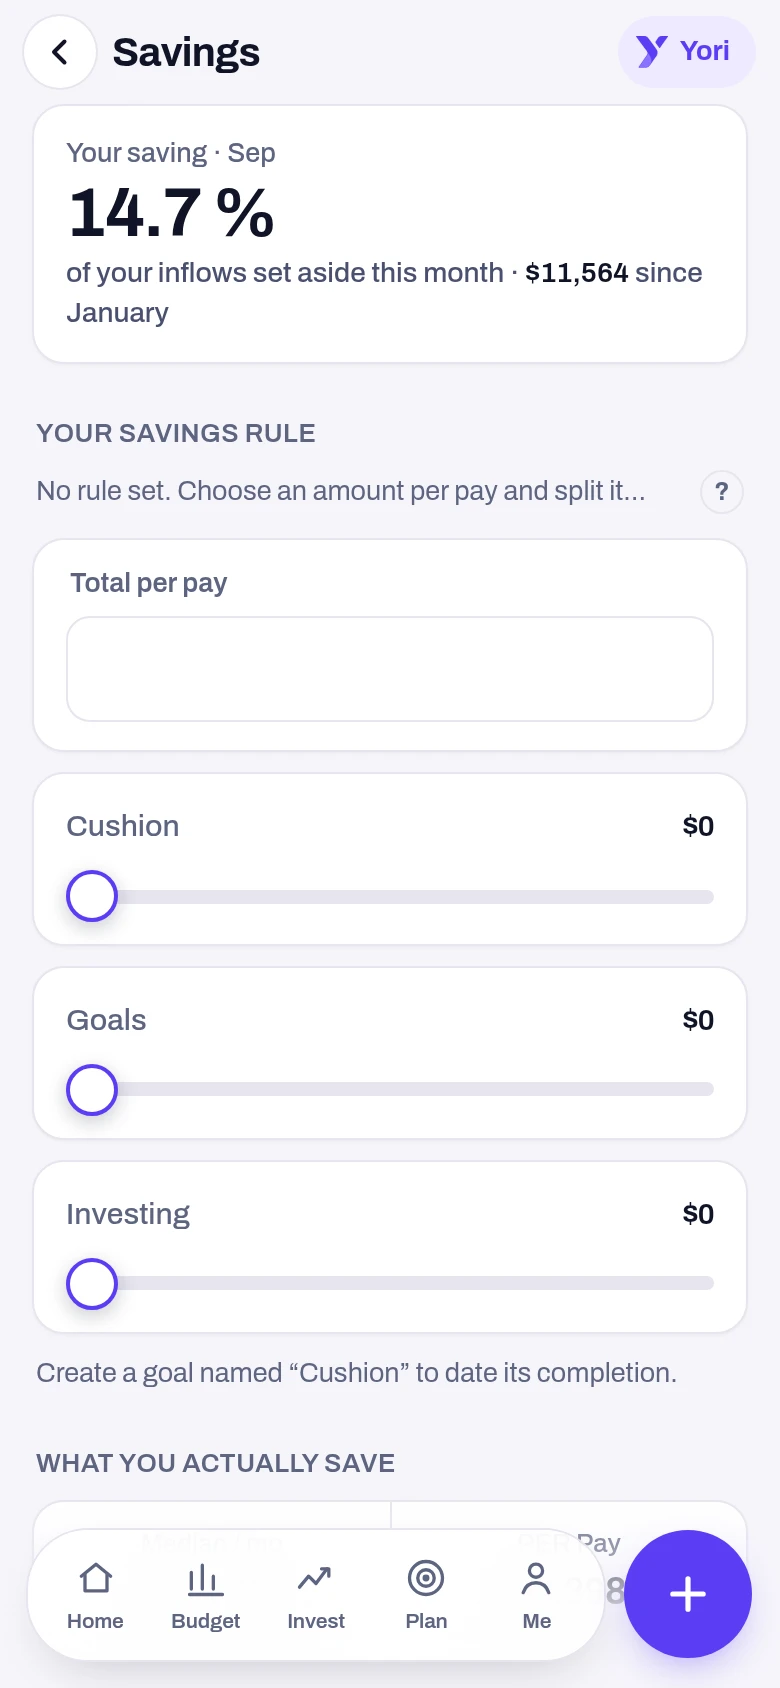
$800 per payday, split before it exists in your account.
The only savings mechanism that holds over time: an amount leaves on the day you get paid, not at the end of the month with whatever is left. $800 on an income of $4,350 is 18.4% of what you earn.
One amount, three destinations decided in advance.
A single savings transfer always ends up being used for something else. Yoseri splits the $800 into three named lines: $300 to the cushion, $200 to dated goals, $300 to investments.
$15,870 saved, and Yoseri tells you at what rate each dollar is sleeping.
Three pockets, three different regimes. A liquid amount and an invested amount are not the same money — that distinction is what the whole job-loss simulation rests on.
“What if I lost my job?” — 3.1 months. That is the answer.
The simulation guesses nothing. It adds up what you have — $6,320 of cushion, $3,600 of sellable investments — and divides by what you spend: $3,160 a month, debt payments included. 9,920 ÷ 3,160 = 3.1 months.
Cutting 20% of your non-debt spending — $364 a month — takes you from 3.1 to 3.5 months of runway. It is the quickest lever you have, and the only one that depends on nobody but you.
A goal with no date is a wish.
Three goals, $12,270 saved out of $46,480 targeted, or 26% of the way. Lisbon has slipped a month: it is written on the line, not hidden in a total.
$1,556 a year is $129.67 a month. And four years off your down payment.
An annual saving means nothing until it is tied to a date. The two easiest alone are worth $756 — that is 3.8 months of your down payment.
What people ask us about savings.
A rule, a cushion, dated goals — with the time it takes before the first figure means anything.
Does Yoseri make the $800 transfer for me?+
No, and it has no technical power to do so. The transfer stays at your bank — Yoseri tracks it, works out the dates and warns you when it breaks.
Why is my cushion 2.0 months if I have $6,320 set aside?+
A cushion is counted in months of spending, not in dollars. You spend $3,160 a month on average, debt payments included. 6,320 ÷ 3,160 = 2.0 months.
Why does the simulation say 3.1 months when my cushion is 2.0?+
If things went wrong, you would not live on your cushion alone: the simulation adds your $3,600 of sellable investments. (6,320 + 3,600) ÷ 3,160 = 3.1 months. Your debt payments stay counted — nothing is suspended at your creditors.
Why does my savings rate show 18.4% in one place and 16.2% in another?+
Because they are two different measures, and neither is wrong. 18.4% is the current month: $800 saved on $4,350 received in August. 16.2% is the last twelve months: $9,600 on $59,248 received.
What happens if I miss a payment?+
Nothing catches up on its own, and the date moves. On your down payment, 2 payments missed out of 30 are already built into the 2038 date: it is calculated not on the promised payment, but on the payment received.
Are the goals and scenarios in the free plan?+
Yes. The rule, the three pockets, the cushion, the dated goals and the job-loss simulation all work with manual entry, with no banking credentials.
The savings that trigger without you.
A rule on every payday, a dated goal, and the arrival date that recalculates itself.
The demo runs on test data. No banking credentials are asked for.
Further reading on this.
Yoseri’s publication unpacks these mechanisms with the maths shown, using worked figures you can redo by hand.
How many months in your cushion? "Three" is a lazy answer
The three-month rule circulates everywhere without ever saying three months of what. The right calculation depends on your real spending, the debts you must service and how stable your income is.
· 5 min The GlossarySavings rate
The share of your net income you do not spend. The most predictive indicator of where you are heading — and the easiest to dress up.
· 1 min The GlossaryVariance
Your results swing naturally around their average. A bad year does not prove your method is broken — and a good year does not prove it works.
· 1 min The Breakdown“How much should I save a month” has no answer in percentages
The question assumes one destination. There are three, they do not pay the same, and the order you fill them in is worth more than the amount you put in.
· 5 min The Short“Saving up for a trip” is not a goal
An amount with no date cannot be tracked: nothing says whether you are ahead or behind. Add the date and the same goal becomes a division you can check every month.
· 2 min The GlossaryRule of 72
Divide 72 by your rate: you get the number of years to double. A division you can do in your head, and it works on your debt as well as on your savings.
· 1 min